Almost half of Belgian women who retired in 2024 had no supplementary pension at all. Among those who did, they had built up far less money than men. The figures come from an analysis by insurance broker Vanbreda Risk & Benefits.
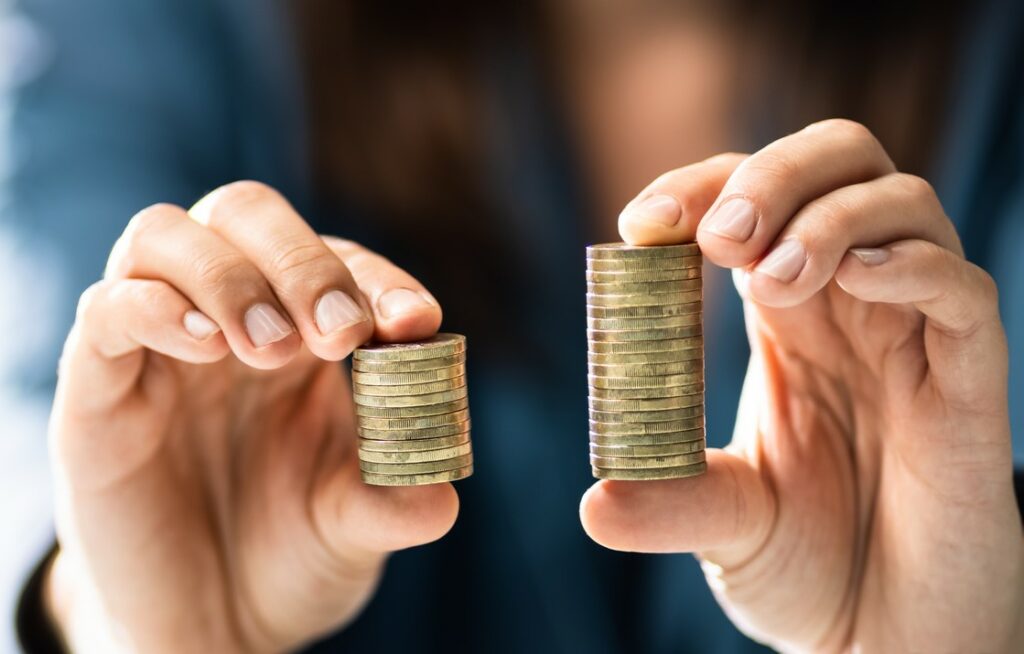
For every €18,000 a man has built up in a supplementary pension, a woman has just under €6,000. Meanwhile, almost half of women retiring in Belgium have no supplementary pension at all.
That is the picture emerging from an analysis by insurance broker Vanbreda Risk & Benefits of people who retired in 2024.
Belgian pensions are built around several pillars: the statutory pension and a supplementary pension. This latter pension is built up through employment, and it is here that the difference between men and women is particularly striking.
Women are less likely to have a supplementary pension
Of the 114,862 Belgians who retired time in 2024, 69% of men had a supplementary pension. Among women, the figure was just 51%. That means almost half of the women in the group had no supplementary pension at all.
Men had built up an average of €100,766 in supplementary pension capital. For women, the average was €46,933.
But the average does not tell the whole story, as a small group of people with very large pension payments can push the figure upwards.
The median gives a better picture of what a typical pensioner has built up. It shows that for men, the median supplementary pension was €18,275, compared with just €5,830 for women. In other words, the typical woman had built up about 68% less than the typical man.
"The average is pushed up by a small group receiving very large payments. The median gives a better picture of the typical pensioner," Franky Stevens, pensions expert at Vanbreda Risk & Benefits, told Het Nieuwsblad.
A double disadvantage
Women therefore face a double disadvantage: they are less likely to have a supplementary pension in the first place, and when they do have one, they generally have accumulated much less.
According to Vanbreda, the gap in supplementary pension capital increased from 44% in 2019 to 53% in 2024. The difference was particularly large among married pensioners, where the gap reached 60%. Among unmarried pensioners, it was 10%.
When statutory and supplementary pensions are combined, women who retired in 2024 received 21% less than men, according to the analysis.
The wider picture is also striking. Figures by European statistics agency Eurostat show that in 2024, women aged 65 and over in Belgium received pensions that were on average 31% lower than men's. Across the EU, the average gap was 24.5%.
The Eurostat figures are not directly comparable with the Vanbreda figures, as they cover a different group and measure pension income in a different way, but both point to a substantial difference between men's and women's retirement income.
Where does the gap come from?
Part of the explanation can be found in people's working lives: women are more likely to work in sectors such as healthcare, social care, and education. Men, meanwhile, are more strongly represented in sectors such as industry, construction, transport and energy.
Supplementary pensions also tend to be higher in some of the sectors where more men work.
Working fewer hours can make the difference even bigger. As pension contributions are linked to earnings, someone who works part-time therefore generally pays less into their supplementary pension than someone working full-time.
Career breaks can have a similar effect. Time spent out of paid employment means fewer contributions and fewer years in which pension savings can grow.
What could change?
The Federal Government plans to raise the minimum employer contribution to supplementary pensions to 3% of actual earnings across sectors by 2035.
Vanbreda Risk & Benefits' Stevens points out that a 3% contribution on a part-time wage is still lower than 3% on a full-time wage. He has therefore argued for a minimum contribution in euros, rather than relying only on a percentage of salary. He also suggests that pension schemes should be subject to a mandatory gender impact assessment.
Stijn Baert, professor of Labour Economics at Ghent University, points to another factor, which he called the "motherhood penalty".
Women's income often changes after they have children, partly because care responsibilities are not always divided equally between parents.
“Women pay the price for having children and taking on a caregiving role. Society as a whole reaps the benefits of female fertility, yet the women themselves are not rewarded for it,” he told Het Nieuwsblad
Baert does not see a simple solution. However, in his belief, the government can also play a role by discussing how paid work and childcare are divided, and by encouraging fathers to take on more care responsibilities.
For people retiring today, however, many of those choices were made decades ago. The figures show how differences in work, pay and career breaks can follow people all the way into retirement.
